Bahar Yakar and Emir Yildirim
18 November 2026•Update: 18 November 2026
Global insurance markets cannot absorb the mounting costs of climate-related disasters without greater investment in resilience, prevention and adaptation, a senior Insurance Europe official told Anadolu.
Nicolas Jeanmart, head of personal and general insurance at Insurance Europe, spoke on the sidelines of the UN's 31st Conference of the Parties (COP31) climate summit in Antalya during an Insurance House event organized by the Turkish Insurance Association.
Jeanmart said events such as COP31 provide an important platform for global leaders to focus on cutting carbon emissions and accelerating adaptation to climate impacts already being felt.
“Insurers provide financial protection when losses occur, but their role goes much further,” he said. “Through risk data, modeling and claims experience, insurers can help governments, businesses and individuals better understand climate-related risks and identify measures to reduce them — this role in prevention is becoming ever more important with risks increasing in frequency and intensity.”
“At the same time, insurers are major long-term investors and have an important role to play in supporting the transition towards a more sustainable economy,” he added.
Jeanmart said climate change is reshaping the risk landscape, requiring insurers to adapt how they assess and manage risks.
He urged the industry to make greater use of forward-looking data and models that account for changes in hazards, exposure and vulnerability.
However, he stressed that adjusting insurance products alone would not be enough to address growing climate risks, emphasizing the importance of prevention and adaptation.
“If we want insurance to remain available and affordable over the long term, we need to reduce the underlying risks through more resilient infrastructure, appropriate land-use planning, stronger building standards and practical measures that households and businesses can take to protect their properties,” he said. “Insurers can contribute their risk expertise and claims experience, provide practical prevention advice and, where appropriate, recognize effective risk-reduction measures in their underwriting.”
Jeanmart also highlighted the insurance protection gap in Europe, saying its causes vary across countries depending on exposure to natural hazards, insurance market structures, public compensation schemes, risk awareness and prevention efforts.
“Households and businesses may underestimate the risks they face or, in some cases, expect public authorities to provide compensation following a major disaster; this can reduce incentives to take out adequate insurance protection in advance,” he said.
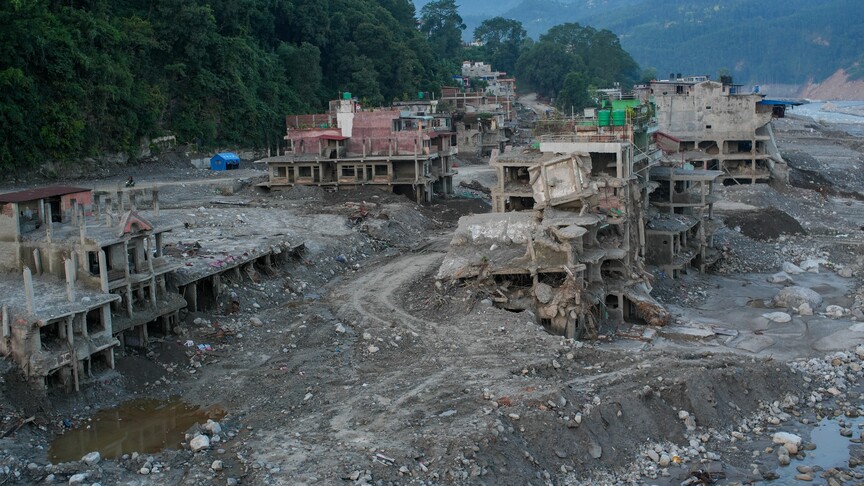
He identified insufficient investment in resilience as another major concern, pointing to continued housing development in areas at high risk of flooding.
“Resilience needs to put at the center of all decisions; indeed, the most sustainable way to preserve affordable and available insurance is to reduce expected losses through prevention and adaptation,” he added.